01
Business Interruption Ignored
Your building gets an estimate. Your downtime gets ignored. We build the lost-income claim from your real numbers — revenue, payroll, rent — so the check covers the closure, not just the drywall.
Commercial and condo claims involve lost income, association bylaws, and layered policies that point at each other — and insurers use that complexity to underpay. We document the full loss — structure, contents, and business interruption — and fight for everything your policies cover.
Free Commercial Claim Review
No obligation. We respond within 1 hour during business hours.
Where Commercial Claims Lose Money
Commercial and condo claims are bigger, slower, and harder-fought than residential ones. Here are the six ways insurers shrink them — and how we push back.
Your building gets an estimate. Your downtime gets ignored. We build the lost-income claim from your real numbers — revenue, payroll, rent — so the check covers the closure, not just the drywall.
The association blames your policy. Your policy blames the association. Meanwhile, nobody pays. We read the bylaws and both policies, pin down who owes what, and go after each carrier for its share.
On big losses, carriers argue you were underinsured and shrink the payout with a formula. We challenge their math, prove what rebuilding actually costs, and fight penalties that don’t hold up.
An older building can’t be rebuilt to old code — sprinklers, electrical, accessibility all cost more today. We scope what today’s code requires and claim the ordinance & law coverage you’re already paying for.
Carriers hold back six figures in depreciation and hope you never come back for it. We track every dollar they withhold, document the repairs, and collect the rest of what your policy owes.
Past 20 years old, every building gets the same excuse: it was old, not damaged. We prove the difference — moisture maps, thermal images, and engineering reports that hold up in a dispute.
Real Results — Large & Complex Losses
Millions recovered on claims that were denied or severely underpaid before we stepped in.
Step-by-Step
From free review to final settlement — here's exactly how we run a commercial or condo loss.
We review your full policy stack — property, business interruption, ordinance & law, and any association coverage — and give you a straight assessment of what the loss should be worth. No charge, no obligation.
We inspect and document at commercial scale: moisture mapping, thermal imaging, licensed contractor scoping, contents inventory — plus the financial records that support a business interruption claim.
We prepare and submit the complete claim package: estimate of loss, photographic record, expert reports, business-income worksheets, and code-upgrade scope — filed correctly the first time, so the carrier has nothing to stall on.
We negotiate directly with the carrier's large-loss team. If they stall or lowball, we invoke the appraisal clause — a binding mechanism that brings in a neutral umpire to resolve the dispute. Most claims settle before reaching that stage.
Where We Work
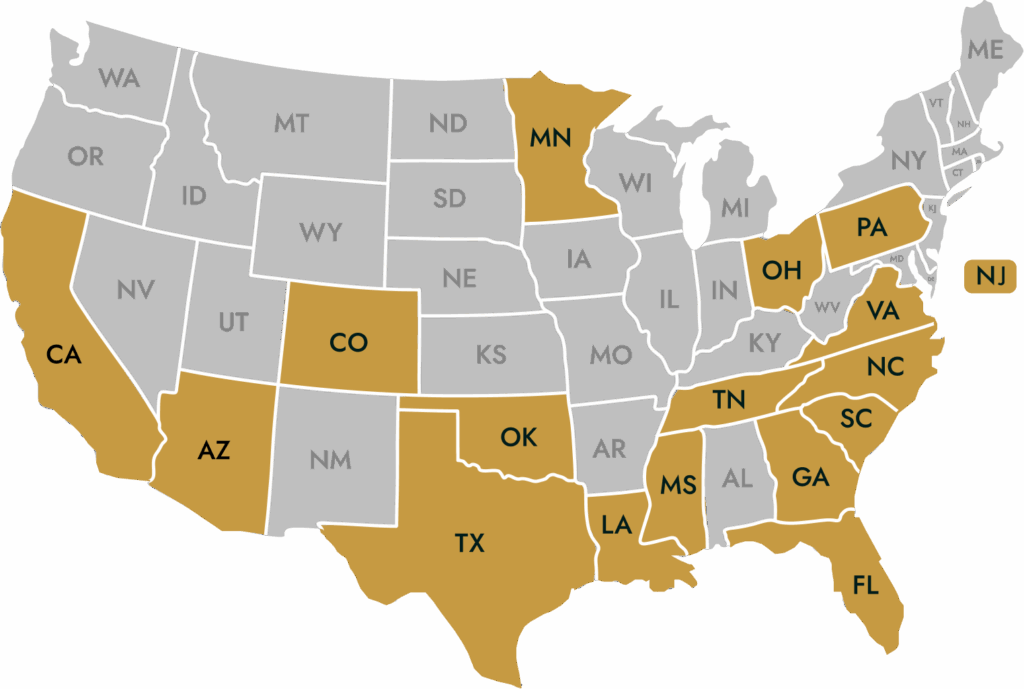
Greenlight Claims is licensed in 18 states and territories. Wherever your property is, we can fight for your claim.
Often both. The association’s master policy covers common elements and, depending on the bylaws, certain building components; your HO-6 covers the unit interior and improvements. We read the bylaws against both policies, determine which carrier owes what, and manage both claims so nothing falls into the gap between them.
If your policy includes business interruption coverage, it can pay lost net income and continuing expenses — payroll, rent, utilities — during the restoration period, plus extra expense coverage to keep you operating. It is one of the most under-claimed coverages we see. We quantify it from your financial records and pursue it alongside the property claim.
The appraisal clause is a provision in most property policies that allows either party to demand a binding, independent appraisal when there's a dispute over the amount of loss. Each side selects a licensed appraiser and they agree on a neutral umpire. The umpire's award is binding on both parties. This process bypasses insurer stonewalling and often results in a significantly higher settlement — without litigation.
Yes — that is normal for us. We report to boards, coordinate with property managers and restoration vendors, attend association meetings when needed, and keep the documentation organized so decisions get made quickly. You get one point of contact for the entire claim.
Nothing upfront. We work on a contingency basis — our fee is a percentage of what we recover for you. If we don't recover for you, you owe us nothing. The free claim review is also completely no-obligation. You take no financial risk by having us evaluate your loss.
Free Commercial Claim Review
Tell us about your commercial or condo loss and we'll respond within one hour with a straight assessment: what your policies should cover, what documentation we would build, and what a realistic settlement path looks like. No cost, no obligation.
No obligation · We respond within 1 hour
THIS IS A SOLICITATION FOR BUSINESS. IF YOU HAVE HAD A CLAIM FOR AN INSURED PROPERTY LOSS OR DAMAGE AND YOU ARE SATISFIED WITH THE PAYMENT BY YOUR INSURER, YOU MAY DISREGARD THIS ADVERTISEMENT.